Qualified Opportunity Zones

Qualified Opportunity Zones (QOZs) represent one of the most compelling tax-advantaged investment strategies supporting long-term economic development in designated communities. A refreshed, permanent Qualified Opportunity Zone program (QOZ 2.0) is being created from the original, with enhancements to streamline the structure of the program.

QOZs Made Permanent Starting January 1, 2027

QOZs & QOFs Explained

The QOZ program was created to revitalize economically distressed communities using private investments. Defined under the 2017 Tax Cuts and Jobs Act, QOZs are census tracts (permanent statistical subdivisions of a county) composed of economically disadvantaged communities. The census tracts are currently being reviewed and after the nomination process concludes, the Secretary of the Treasury will designate and certify the nominated census tracts as QOZs. The IRS and Treasury are expected to officially publish newly designated QOZs in December 2026, which will go effective January 1, 2027.

A Qualified Opportunity Fund (QOF) is an investment vehicle typically structured as a partnership or corporation for U.S. federal income tax pruposes and is responsible for investing in QOZ property or properties. QOFs are required to hold at least 90 percent of their assets in QOZ businesses and assets and are required to meet additional requirements.
QOZ Construction Image

Claim Refined Tax Benefits Now

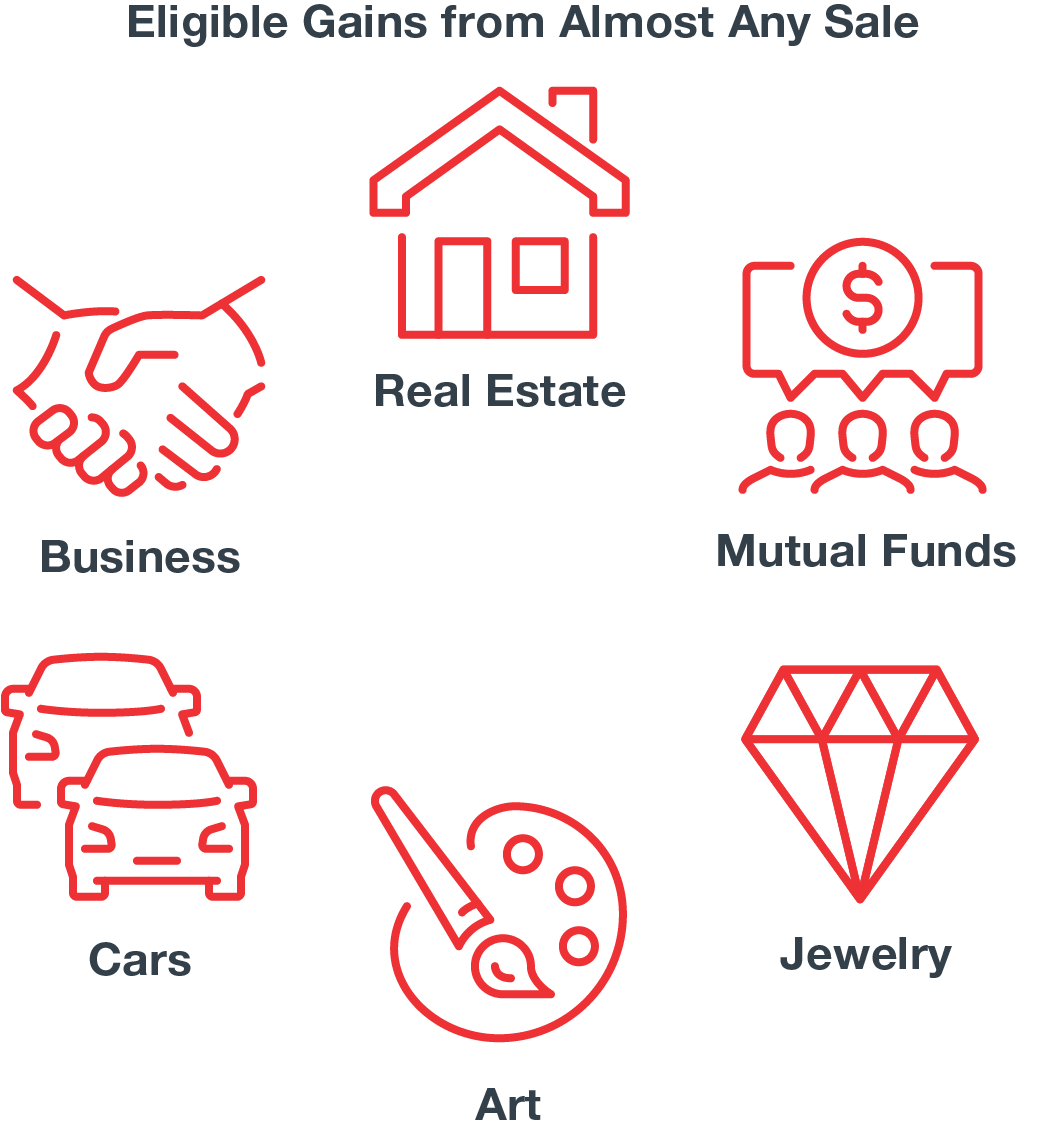
An individual who reinvests capital gain in an eligible QOF is potentially suitable for favorable tax treatment in the form of tax deferral, potential gain reduction, and tax-free appreciation after a 10-year hold, based on QOZ 2.0 reforms. Taxable gains from the sale or exchange of virtually any type of property may potentially be deferred by reinvesting such proceeds in a QOF within 180 days of the sale or exchange (exceptions exist for gain from passthrough entities).

  • 5-year rolling capital gains deferral
  • Reduction of deferred gain after 5 years (10% basis step-up; 30% step-up for certain rural investments)
  • 100% tax elimination after 10+ year hold on QOF
EligibleGains_Chart copy

QOZ 2.0 Important Dates and Deadlines
calendar
July 1, 2026

State governors can propose a new set of QOZ census tracts for federal approval and by integrating acquisitions, dispositions, financing, market intelligence, underwriting, and due diligence, Inland can optimize identifying and evaluating newly designated QOZ 2.0 census tracts as potential investment opportunities.

calendar
October 28, 2026

State nomination deadline to identify new Opportunity Zones, which include a standard 30-day extension to the nomination period

calendar
December 2026

IRS and Treasury officially publish new Opportunity Zones

calendar
January 1, 2027

Kick-off of new QOZ 2.0 program

QOZ Investment Timeline

The timeline below highlights the key tax benefits of a QOF investment, including the five-year tax deferral, potential basis step-up, and opportunity for tax-free growth after a 10-year hold.
  • 2027

    Sale of Original Investment ($1M gains realized)

    Investor realizes gain on original investment and invests gain into QOF

    Capital gain tax is deferred and 5-year deferral clock starts on the investment date

  • 2032

    Deferred Gain Recognition Date with Basis Step-Up (5-year anniversary)

    Investor pays deferred tax on original investment, but basis step-up reduces the recognized deferred gain by 10% for standard QOZ investment or 30% for qualified rural opportunity fund investment

  • 2037

    10-Year Exemption on $1M QOF Investment

    After 10-year holding period, appreciation on a qualifying QOF investment is exempt from federal income tax

  • 2057

    End of Rolling Gain-Exclusion Period

    Investors generally have through 2057 to realize qualifying appreciation with the benefit of the federal income tax exclusion

Understanding QOZ Eligibility

The first day of the 180-day period to reinvest gains into a QOF generally is the date on which the gain would be recognized for federal income tax purposes. Regulations provide that taxpayers that are eligible to elect gain deferral include:

  1. Individuals
  2. C Corporations (including regulated investment companies (RICs) and real estate investment trusts (REITs)
  3. Partnerships
  4. Certain other pass-through entities

Calculate Your QOZ Investment Window

Investors have 180 days from a taxable event to invest in a QOZ to access significant tax advantages. Enter the date of your taxable event below to calculate your QOZ investment deadline.

Note: This calculator applies the general 180-day rule. Special rules may apply to gains from partnerships, S corporations, trusts, installment sales, REITs, RICs, and other pass-through investments, which may permit a different start date for the 180-day investment period. Consult your tax advisor regarding your specific circumstances.

QOZ 2.0 FAQ

The updated Qualified Opportunity Zone program introduces new rules, timelines and potential tax benefits for investors. Explore the frequently asked questions below for a closer look at QOZ 2.0, including how it compares with the original program and what the changes may mean for future investments.

What are the key regulatory changes under QOZ 2.0?

Answer: QOZ 2.0 makes the Qualified Opportunity Zone ("QOZ") program permanent and introduces several changes intended to strengthen the program. These include, but are not limited to, tighter rules around eligible census tracts, refreshed QOZ designations every 10 years, a new category for Qualified Rural Opportunity Funds and more extensive sponsor-level reporting requirements designed to improve transparency around capital deployment, community impact, and investor reporting. Explore a side-by-side comparison of QOZ 1.0 vs. 2.0 here. 

Does “permanent” mean QOZ 2.0 benefits are available continuously or that the program relaunches every 10 years?

Answer: “Permanent” means the QOZ program is no longer tied to a single sunset date, and investors may access the benefits on a "rolling" basis. Each qualifying investment generally starts its own tax benefit timeline, including a five-year gain deferral period, a 10% reduction in deferred gain after five years, and the potential for tax-free appreciation after a 10-year hold. 

Separately, the QOZ census tracks are expected to be refreshed every 10 years, creating a recurring process to identify newly eligible communities and help ensure capital continues flowing to areas with meaningful need for investment. 

What are the core tax benefits of QOZ 2.0?

Answer: Under QOZ 2.0, the core tax benefits of the original QOZ program generally remain in place: tax deferral, tax reduction, and the potential for tax-free appreciation after a 10-year hold. Specifically, investors may defer eligible capital gains for five years by investing in a Qualified Opportunity Fund ("QOF"). If the QOF investment is held for five years, 10% of the deferred gain may be reduced. Qualified Rural Opportunity Funds ("QROF") may offer an enhanced 30% reduction in capital gains tax. If the QOF or QROF investment is held for at least 10 years, any appreciation on the QOF may be excluded from capital gains tax.

Can a deferred QOZ 1.0 gain be reinvested into a QOZ 2.0 investment for additional deferral?

Answer: According to IRS guidance, a deferred QOZ 1.0 gain that becomes taxable on December 31, 2026, generally cannot be reinvested into a QOZ 2.0 investment for an additional deferral. Once an investor has made a QOZ 1.0 investment and elected to defer a capital gain, that deferral benefit has been utilized. As a result, the same gain cannot qualify for a second deferral under QOZ 2.0.

Are QOZ 1.0 census tracks grandfathered into QOZ 2.0?

Answer: Not automatically. Some QOZ 1.0 tracts may be redesignated under QOZ 2.0, while others may no longer qualify. New tracts that were not part of QOZ 1.0 may also be selected.

Can 2026 capital gains be invested in a QOZ 2.0 fund, and would the QOZ 2.0 deferral apply?

Answer: Yes. Investors have 180 days from the date a gain is recognized to reinvest eligible capital gains in a QOF. If the capital gain is realized in the latter part of 2026 or through a passthrough entity, the 180-day period to invest in a QOF could extend past January 1, 2027 such that the QOF investment closed after such date could qualify under QOZ 2.0. In that case, the applicable QOZ 2.0 deferral would run for five years from the date of the new investment, subject to the investor’s specific facts, timing and applicable tax rules. Investors should consult their tax advisor for specific details. 

What happens to deferred QOZ 2.0 gains at the end of the five-year period? How does the 10% basis step-up reduce the amount taxed?

Answer: Under QOZ 2.0, eligible capital gains invested in a QOF may be deferred for five years. At the end of that five-year deferral period, the deferred gain becomes taxable. However, if the investor has held the QOF investment for the full five years, the investor generally receives a 10% basis step-up, which effectively excludes 10% of the original deferred gain from taxation.

For example, if an investor invests a $1 million capital gain into a QOF, that capital gain is deferred for five years. If the investor holds the QOF investment for five years, the 10% basis step-up would reduce the taxable deferred gain by $100,000. As a result, the investor would generally pay tax on $900,000 of the original deferred gain, rather than the full $1 million. QROFs may offer an enhanced 30% basis step-up, which could reduce the taxable deferred gain even further. 

What happens if capital gains tax rates change during the deferral period?

Answer: The investor typically recognizes the deferred gain at the tax rate in effect when the gain becomes taxable at the end of the five-year deferral period. As was the case under QOZ 1.0, if tax rates increase, the investor may owe more tax than they would have at the time of the original sale; however, the deferral also provides the potential benefit of retaining and investing those tax dollars during the five-year period.

Is it a requirement to exit a QOF investment after 10 years?

Answer: No. The 10-year mark is the minimum holding period required to receive the tax-free appreciation benefit. Investors may continue holding the investment beyond 10 years, potentially up to 30 years, allowing appreciation to continue growing tax-free, subject to the applicable rules.  

Does the 10-year clock start when the QOF closes its subscription window?

Answer: No. Under QOZ 2.0, the 10-year holding period begins when the investor makes their investment in the QOF, not when the QOF closes its subscription window. For example, an investor who invests on January 1, 2027, would generally reach the 10-year mark on January 1, 2037, while an investor who invests later would have a later 10-year date. The underlying QOF, however, may peg exit of its investments to the last QOF investor to ensure that all QOF investors enjoy the tax-free appreciation benefit. 

How are rural QOZs designated?

Answer: Eligible QOZ census tracts are first identified by the IRS, after which governors nominate and select tracts in their states for review and approval by the IRS and Treasury. QOZ 2.0 also introduces QROFs, which may offer enhanced tax benefits for investments in those areas. Learn more here.

What is the difference between QROFs (rural QOFs) and ordinary QOFs? Are you able to combine them?

Answer: To qualify for the enhanced rural benefits, including the increased basis step-up, a QROF would need to be a standalone QOF with a dedicated rural investment focus. Specifically, a QROF must generally hold at least 90% of its assets in rural QOZ property or businesses. Additionally, funds cannot mix rural and non-rural investments and still receive enhanced rural treatment.

What are the unique benefits for rural areas under QOZ 2.0?

Answer: QROFs (rural QOFs) offer enhanced tax benefits, including a 30% reduction of the deferred gain after a five-year hold, compared to 10% for standard QOFs, and a reduced 50% substantial improvement threshold for the underlying QOZ investment, which potentially makes it easier to deploy capital into qualifying rural QOZ projects. 

What is the status of Puerto Rico and the U.S. Virgin Islands under QOZ 2.0?

Answer: Under QOZ 1.0, the entire island of Puerto Rico was designated as a QOZ. Under QOZ 2.0, that broad designation no longer applies. Instead, Puerto Rico would be reviewed under the updated QOZ 2.0 census tract framework, meaning only certain eligible tracts may qualify as QOZs. As of October 2026, 18 census tracts have been nominated as QOZ for U.S. Virgin Islands, awaiting final U.S. Treasury certification to become effective January 1, 2027. 

QOZ Education & Insights

QOZs
Hear from Inland Leadership and Baker McKenzie on the next generation of Qualified Opportunity Zones.
QOZs
This one page fact sheet outlines the potential benefits of QOZ 2.0 investment opportunities.
Tax Advantaged Strategies
Learn how to maximize the tax deferral benefits of 1031 and 721 exchanges, as well as the process of executing a successful 721...

Who You Invest with Is Everything®

We can help investors connect with a financial professional who can tailor strategies to individual goals, assess suitability, and provide expert guidance throughout the investment process. We encourage financial professionals interested in learning more to connect with us—we’re here to support your clients and your business.